Zaki Ullah Khan v. State of U.P. & Others, 2026
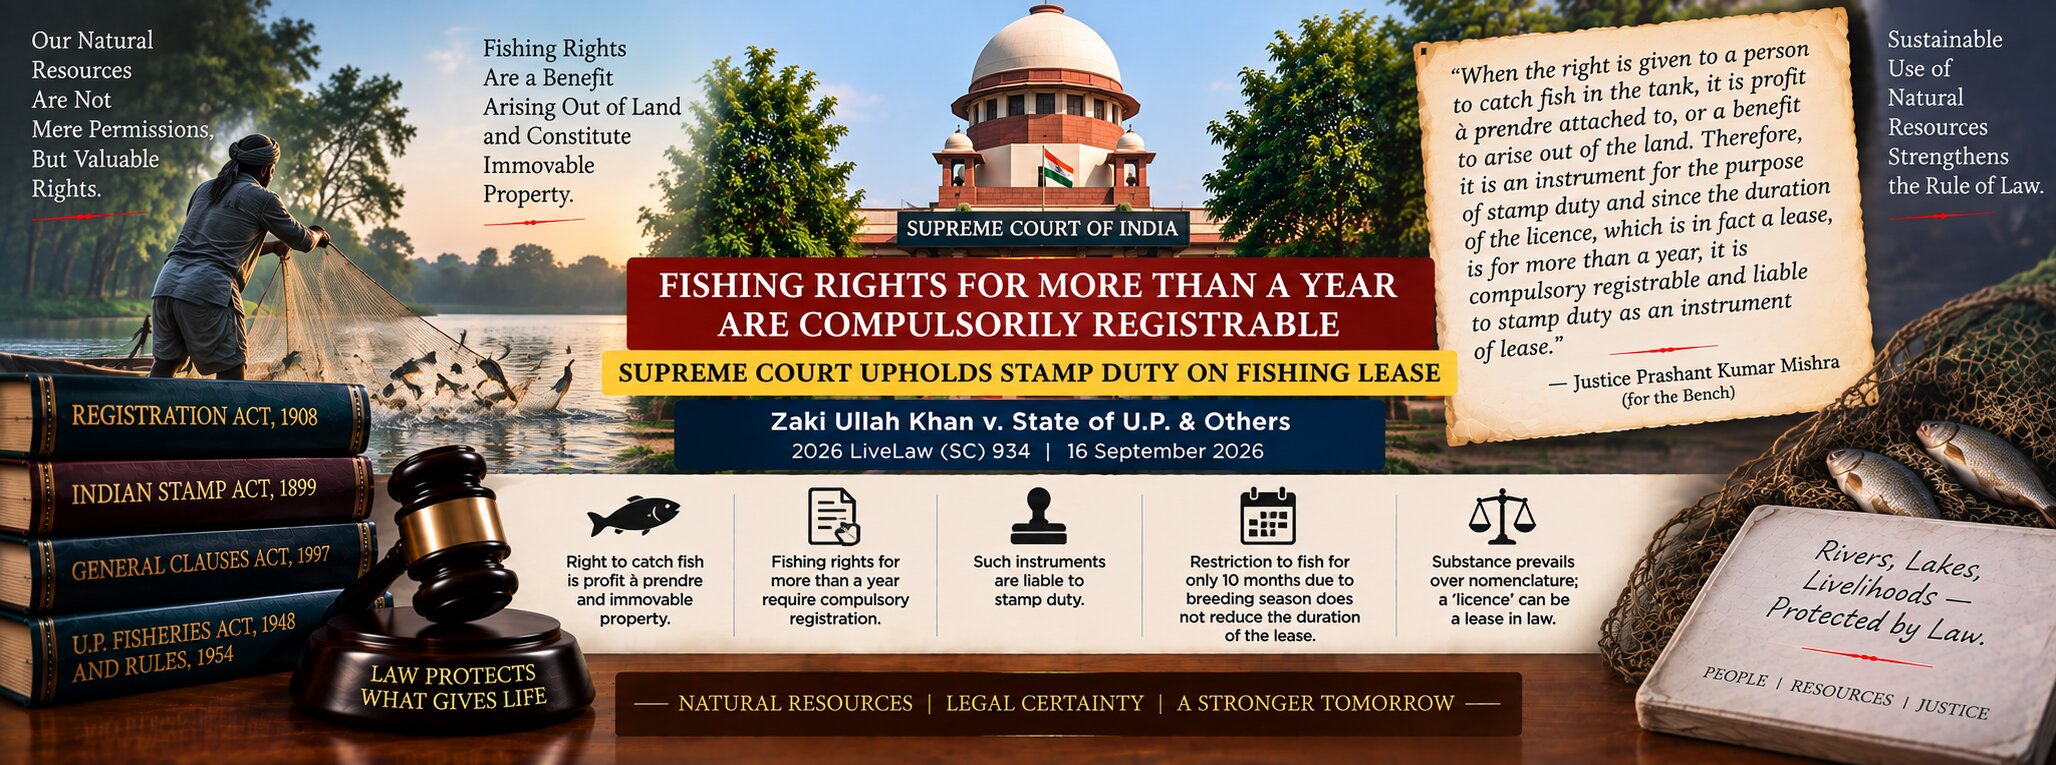
The right to catch fish is profit à prendre.
Judgement Details
Court
Supreme Court of India
Date of Decision
16 September 2026
Judges
Justice Prashant Kumar Mishra and Justice Shree Chandrashekhar
Citation
Acts / Provisions
Facts of the Case
-
The appellant, Zaki Ullah Khan, obtained fishing rights in Sharda Sagar Jalashya, Pilibhit, Uttar Pradesh.
-
The document granting the fishing rights was described as a licence for fishing.
-
The fishing rights were granted for approximately three years, from 1998 to 2001.
-
The authorities treated the document as an instrument having the character of a lease, rather than merely a temporary permission to fish.
-
The Collector, Pilibhit directed the appellant to pay deficit stamp duty of ₹15,72,525.
-
The authorities also considered the document to be compulsorily registrable because the fishing rights had been granted for a period exceeding one year.
-
The appellant challenged the demand before the appropriate authorities and subsequently before the Allahabad High Court.
-
The High Court upheld the decision requiring payment of the deficit stamp duty.
-
The appellant then approached the Supreme Court, arguing that the document was only a fishing licence and should not attract the registration and stamp-duty requirements applicable to a lease.
-
The appellant further argued that fishing was permitted only for 10 months in each year because of restrictions imposed during the breeding season.
-
According to the appellant, this meant that the effective duration of the fishing permission was less than one year.
-
The State contended that the right to catch and carry away fish constituted profit à prendre, namely a benefit arising out of land.
-
The State therefore argued that the fishing right constituted an interest in immovable property for the purposes of stamp duty and registration.
-
The Supreme Court examined whether the fishing right amounted to profit à prendre and whether the three-year grant was compulsorily registrable.
Issues
-
Whether the right to catch and carry away fish from a water body constitutes profit à prendre and a benefit arising out of land?
-
Whether such a fishing right constitutes immovable property for the purposes of stamp duty and registration?
-
Whether a document granting fishing rights for more than one year is an instrument in the nature of a lease requiring compulsory registration?
-
Whether the statutory restriction permitting fishing for only 10 months in each year reduces the legal duration of a three-year fishing grant?
-
Whether the appellant was liable to pay the deficit stamp duty of ₹15,72,525?
Judgement
-
The Supreme Court dismissed the appeal and upheld the decision of the Allahabad High Court.
-
The Court held that the right to catch and carry away fish from a tank or water body constitutes profit à prendre.
-
Profit à prendre is a benefit arising out of land and therefore falls within the concept of immovable property for the relevant statutory purposes.
-
The Court relied upon the Constitution Bench judgment in Anand Behera v. State of Orissa, which recognised fishing rights as profit à prendre.
-
Although the document was described as a licence, its substance and duration showed that it operated as an instrument in the nature of a lease.
-
Since the fishing rights were granted for more than one year, the document was compulsorily registrable under Section 17(1)(d) of the Registration Act, 1908.
-
The Court rejected the argument that fishing being permitted for only 10 months annually reduced the duration of the licence.
-
The restriction was imposed under the U.P. Fisheries Act and Rules for regulatory purposes, particularly during breeding seasons.
-
Such a statutory restriction regulated the exercise of the fishing right but did not reduce the contractual duration of the grant.
-
The appellant was consequently liable to pay the appropriate stamp duty, including the deficit amount determined by the authorities.
Held
-
Profit à prendre constitutes a benefit arising out of land.
-
Such a fishing right is treated as immovable property for the relevant purposes of stamp duty and registration.
-
A fishing-rights instrument granted for a period exceeding one year is compulsorily registrable.
-
The instrument is also liable to stamp duty as an instrument in the nature of a lease.
-
A prohibition on fishing during particular months due to breeding-season regulations does not shorten the duration of the underlying grant.
-
The fact that actual fishing could take place for only 10 months in a year did not transform the three-year grant into a grant of less than one year.
-
The appellant was liable for the deficit stamp duty of ₹15,72,525.
-
The Supreme Court therefore dismissed the appeal.
Analysis
-
The key legal concept in the case is profit à prendre, meaning a right to take some benefit or produce from another person's land.
-
The Court considered the right to catch and remove fish from the water body to be a direct benefit arising from that property.
-
Consequently, the fishing right acquired the character of immovable property for stamp-duty and registration purposes.
-
The judgment demonstrates that the name or label of an instrument is not conclusive in determining its legal character.
-
A document described as a licence can, depending upon its terms and substance, operate as a lease or an interest in immovable property.
-
The duration of the grant was crucial because it extended beyond the statutory one-year threshold.
-
The Court made an important distinction between the duration of the right and the period during which the right could actually be exercised.
-
The 10-month fishing restriction was a statutory regulatory measure and did not terminate or reduce the three-year grant.
-
The judgment reinforces the principle of substance over nomenclature in determining the legal nature of an instrument.
-
The decision reaffirmed the importance of Anand Behera v. State of Orissa in determining the legal character of fishing rights.
-
The ruling is relevant to government fisheries contracts, water-body leases, fishing auctions, stamp-duty assessment and registration of property-related instruments.
-
It also highlights that parties cannot avoid stamp duty and registration requirements merely by describing a long-term property-related right as a “licence.”