V. Sumitra Reddy & Anr. v. K. Ranganadha Reddy & Ors., 2026
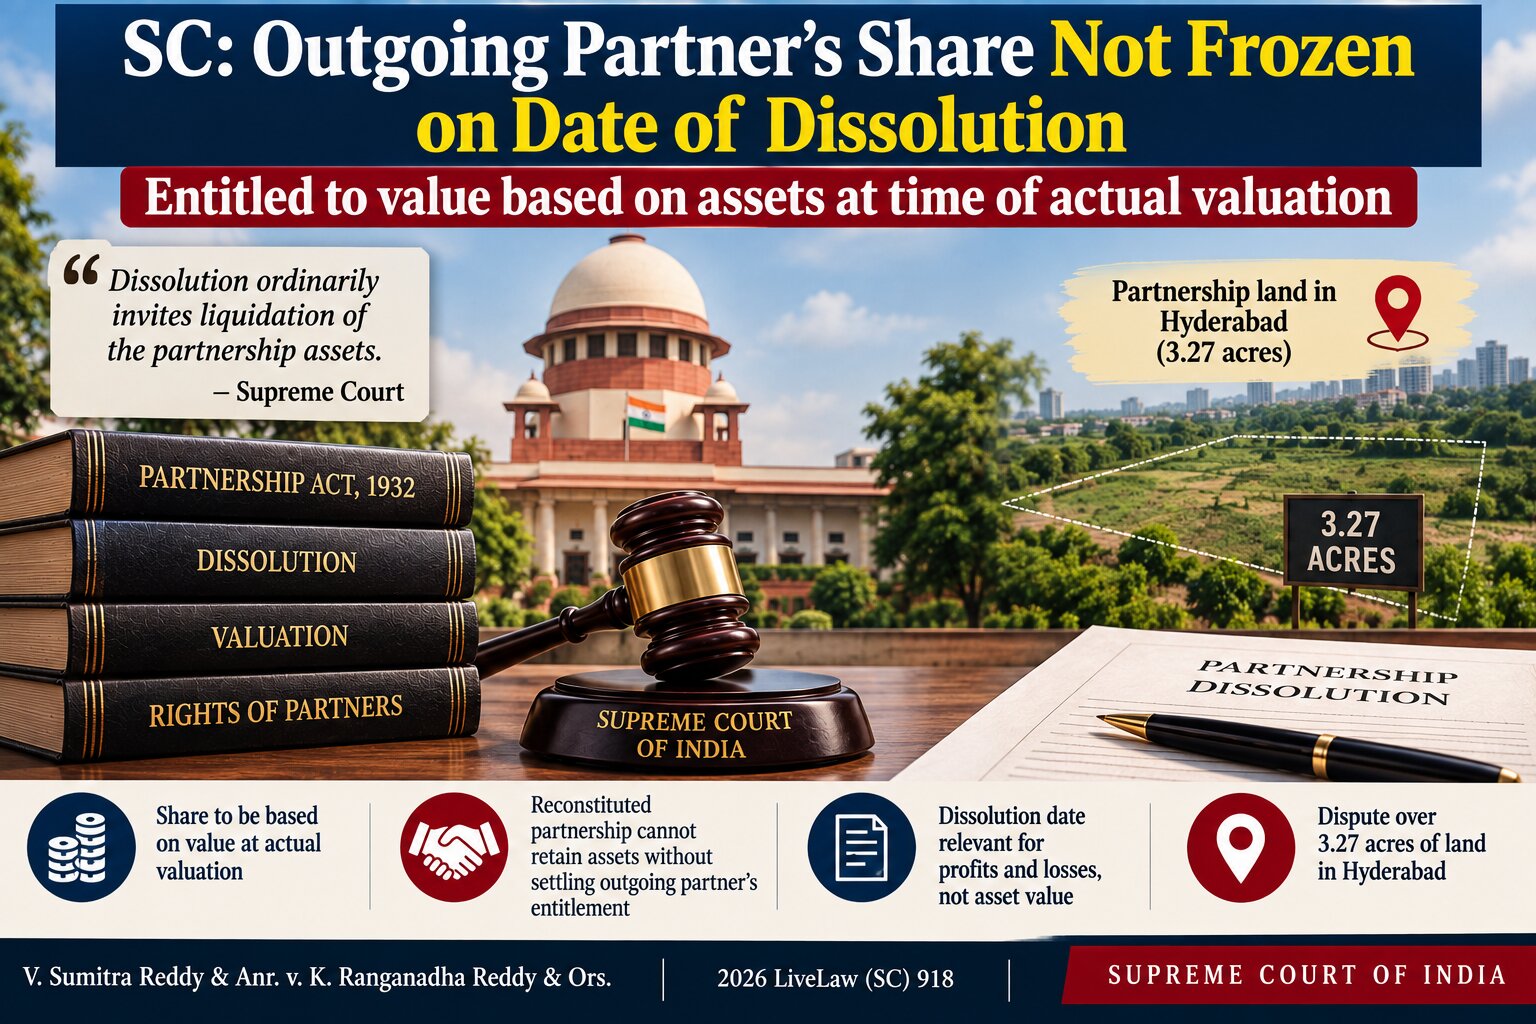
The value of an outgoing partner's share in the residue of partnership assets is not necessarily frozen on the date of dissolution.
Judgement Details
Court
Supreme Court of India
Date of Decision
8 September 2026
Judges
Justice Ujjal Bhuyan and Justice Vipul M. Pancholi
Citation
Acts / Provisions
Facts of the Case
- The dispute concerned a partnership firm owning approximately 3.27 acres of land in Hyderabad.
-
The partnership was a partnership at will.
-
One of the partners exercised the right to dissolve the partnership.
-
The partnership stood dissolved on 18 October 1983.
-
A dispute subsequently arose regarding the entitlement of the outgoing partner to his share in the partnership assets.
-
The principal dispute concerned the valuation date for determining the outgoing partner's share in the partnership's immovable property.
-
One side contended that the outgoing partner's share should be valued as on the date of dissolution, i.e. 18 October 1983.
-
The opposing position was that the value should be determined when the assets were actually valued or liquidated/sold.
-
The partnership assets included valuable immovable property whose value could change substantially over time.
-
After dissolution, some partners continued the business through a newly constituted/reconstituted partnership.
-
The new partnership continued to retain and utilise the land that belonged to the erstwhile dissolved partnership.
-
The dispute therefore also concerned whether the new partnership could continue to retain the assets of the dissolved firm without first settling the rights of the outgoing partner.
-
The Andhra Pradesh High Court had considered the dispute and ruled in favour of the position that the outgoing partner's entitlement was not required to be frozen at the value existing on the date of dissolution.
-
The matter ultimately reached the Supreme Court.
-
The Supreme Court examined the distinction between the date relevant for determining the profits and losses of the dissolved firm and the date relevant for determining the monetary value of the outgoing partner's share in the residue of partnership assets.
Issues
-
Whether the share of an outgoing partner in the residue of partnership assets must be valued as on the date of dissolution of a partnership at will?
-
Whether the date of dissolution is relevant only for determining the profits and losses of the partnership business and not necessarily for determining the monetary value of the outgoing partner's share in the partnership assets?
-
Whether the value of the outgoing partner's share is required to be determined on the basis of the actual valuation or liquidation of the partnership assets?
-
Whether the remaining partners can retain and utilise the assets of a dissolved partnership for a newly constituted partnership without first settling the outgoing partner's entitlement?
-
Whether the newly constituted partnership can lawfully retain the immovable property of the erstwhile partnership without purchasing the property or otherwise settling the rights of the outgoing partners?
-
Whether the partnership assets must ordinarily be liquidated and their realised value distributed among the partners according to their respective shares when no agreement for settlement is reached?
Judgement
-
The Supreme Court affirmed the judgment of the Andhra Pradesh High Court and dismissed the appeal.
-
The Court held that the date of dissolution, 18 October 1983, was relevant for determining the profits and losses of the partnership business.
-
However, that date did not freeze the monetary value of the outgoing partner's share in the residue of the partnership assets.
-
The Court distinguished between calculating the profits and losses of the firm and determining the value of the partner's share in the partnership assets.
-
The outgoing partner was entitled to have his share determined with reference to the value of the partnership assets at the time of their actual valuation/liquidation.
-
The Court held that dissolution ordinarily requires the liquidation and settlement of the partnership assets and liabilities.
-
If one or more partners wished to retain the partnership assets rather than liquidate them, they could do so by paying the market value of the other partners' shares, subject to an appropriate agreement.
-
The Court held that the newly constituted partnership could not simply retain the assets of the erstwhile dissolved firm without first settling the rights of the outgoing partner.
-
The land continued to belong to the erstwhile partnership, notwithstanding the subsequent formation of a new partnership.
-
The new partnership could have retained the land by purchasing it from the erstwhile partnership or by otherwise settling the outgoing partner's entitlement.
-
Since this had not been done, the Court held that the retention of the land by the new partnership was illegal.
-
The Court emphasised that dissolution is not merely a formal termination of the partnership relationship; it requires appropriate settlement of the partnership assets and accounts.
-
The appeal was accordingly dismissed.
Held
-
The value of an outgoing partner's share in the residue of partnership assets is not necessarily frozen on the date of dissolution.
-
The date of dissolution is relevant for determining the profits and losses of the partnership business.
-
The same date does not necessarily determine the monetary value of the partner's entitlement in the partnership assets.
-
The value of the outgoing partner's share should reflect the value of the partnership assets at the time of actual valuation or liquidation, as applicable.
-
Dissolution ordinarily requires the partnership assets to be liquidated and the value realised to be distributed according to the partners' respective shares.
-
The remaining partners cannot simply appropriate or continue using the assets of the dissolved partnership without settling the rights of the outgoing partner.
-
A newly constituted partnership does not automatically acquire the assets of the erstwhile dissolved partnership merely because some of the same partners continue the business.
-
The new partnership may retain such assets only after purchasing them or otherwise lawfully settling the entitlement of the outgoing partners.
-
The land in question continued to belong to the erstwhile partnership after dissolution until its rights were properly settled.
-
The retention of the land by the new partnership without such settlement was held to be illegal.
Analysis
-
Distinction between dissolution and valuation: The key contribution of the judgment is its distinction between the date on which a partnership dissolves and the date relevant for determining the monetary value of the outgoing partner's share in the partnership assets.
-
Profits versus asset value: The Court made it clear that profits and losses must be calculated with reference to the dissolution date, but this does not mean that the value of an immovable asset must automatically be frozen on that same date.
-
Protection of outgoing partner: If the value of partnership property substantially increases after dissolution but before actual valuation or liquidation, freezing the partner's entitlement at the earlier date could disconnect his share from the actual value of the partnership estate. The Court's approach preserves the outgoing partner's entitlement in the residue.
-
Effect of dissolution: Dissolution triggers the process of settling the partnership's affairs. The partnership property cannot simply be treated as the personal property of the remaining partners.
-
Continuation of business: The judgment draws an important distinction between continuation of business by some former partners and continuation of ownership of the dissolved firm's assets. Formation of a new partnership does not automatically transfer the property of the old partnership to the new firm.
-
Need for settlement: If continuing partners want to retain the assets of the dissolved firm, they must first address the financial entitlement of the outgoing partners through purchase, valuation, settlement or another lawful arrangement.
-
Immovable property: The case is particularly significant because the partnership asset involved valuable land. Property values can change considerably over time, making the question of the correct valuation date especially important.
-
No automatic transfer to reconstituted firm: The Court rejected the proposition that a newly constituted partnership could simply inherit the assets of the dissolved partnership merely because the business continued.
-
Liquidation as the ordinary consequence: Where the partners cannot agree on settlement, liquidation of the partnership assets and distribution of the realised value according to the partners' respective shares becomes the appropriate course.
-
Protection against unilateral retention: The ruling prevents continuing partners from retaining valuable assets of a dissolved firm indefinitely while leaving the outgoing partner to claim only an amount calculated at an outdated asset value.
-
Broader legal principle: The decision reinforces that partnership assets belong to the firm as a collective legal relationship between partners, and their treatment after dissolution must follow the statutory and contractual framework governing settlement of the partnership.
-
Practical significance: For partnerships holding valuable immovable property, the judgment highlights the importance of expressly addressing valuation, buy-out rights, liquidation and transfer of assets when a partner exits or the partnership is dissolved.